Puerto Rico Tourism Update: Record Lodging Performance & Winter Outlook
Lodging Revenue Reaches a New Year-to-Date Record
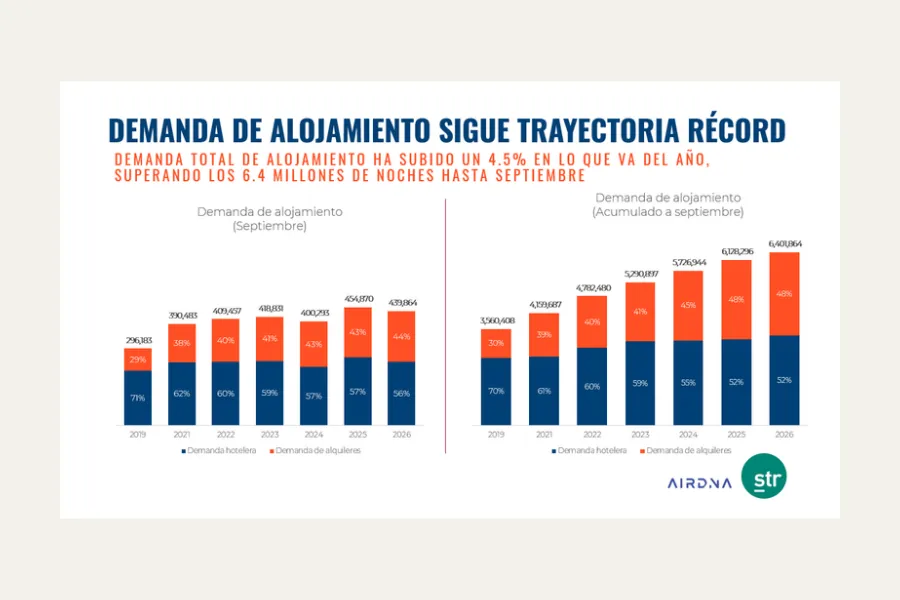
Year-to-date lodging revenue from STR and AirDNA surpassed $1.64 billion through September, up 6.2% compared to last year and the highest level recorded for the period. Hotel revenue rose 6.6% to $1.02 billion, while short-term rental revenue increased 5.5% to $622 million, accounting for 38% of total lodging revenue.
September lodging revenue totaled $87.6 million, 2.3% below September 2025 but 12.7% above September 2024. Hotels generated $54.6 million (-5.5%), as the decline in room nights outweighed a 1% increase in average rate, while rentals generated $33.1 million (+3.5%), supported by gains in both demand and rate.
By region, rentals in San Juan generated $8.7 million in September revenue, with an ADR of $165 and the highest occupancy among the main regions (42%). The West followed with $7.1 million (ADR $165), the East with $5.7 million (ADR $183), and the North region with $2.7 million (ADR $183). Together, these four regions accounted for about 73% of rental revenue across the Island.
SJU Arrivals Return to Growth in September
Arrivals at the San Juan International Airport in September reached 398,000 passengers, about 16,000 more than the same month last year (+4.2%) and the first year-over-year monthly gain of 2026. Year-to-date through September, Aerostar (SJU) has reported 5.08 million passenger arrivals, 3.1% below the same period last year, or approximately 162,000 fewer passengers. In September, arrivals grew from North America (+4.5%), the Caribbean (+9.0%), and Europe (+6.8%). Year-to-date, South America (+10.1%) and Europe (+2.6%) are the only major regions growing, while North America (-2.9%) and the Caribbean (-8.7%) remain below last year.
Spirit Airlines’ closure remains the largest drag on arrivals, with 246,000 fewer passengers year-to-date (-54%) and no arrivals in September, compared with 26,000 a year earlier. Silver Airways’ exit removed another 36,000 passengers. Other carriers continue to offset part of these losses: American Airlines has added nearly 100,000 arrivals year-to-date (+18%) and JetBlue nearly 46,000 (+3%), while Avelo (+77%) and Arajet (+193%) continue to scale. In September, Frontier arrivals grew 51% (+25,000) and American 23%.
New service is also broadening SJU’s market base. New routes this year include JetBlue from Philadelphia and Jacksonville, Frontier from Chicago O’Hare, and new origin markets such as Buffalo, Norfolk, Richmond, and Concord, NC. Philadelphia arrivals nearly doubled in September (+94%) and are up 28% year-to-date. Meanwhile, the San Juan cruise port has welcomed 1.32 million passengers through September, 27% more than the same period last year, although September cruise arrivals declined 25.5% to 69,000.
Lodging Sector Projects a Strong Winter Season
Looking ahead, hotel bookings for the holiday and early winter season are pacing well ahead of last year. As of October 11, 2026, Amadeus Hospitality reports committed hotel occupancy for October at 59.5%, 3.7% below the same point last year, while November (53.2%, +5.6%) and December (44%, +13.6%) are running ahead. Early 2027 is also tracking strongly, with January (30.6%) and February (29.0%) up 13.8% and 18.9% year over year, respectively, while March currently trails slightly (-3.1%).
Local short-term rental activity continues to trend positively, with AirDNA reporting that, as of October 12, 2026, every month through March is pacing ahead in booked listing nights. October bookings are up 4%, November 19%, and December 24%, while the most notable gains are projected for the first quarter of 2027, with January, February, and March up 36%, 37%, and 50% year over year, respectively.
Aligned with the local industry, AirDNA reports that U.S. short-term rental nights on the books are ahead of last year in every month from October through March, ranging from +4.0% in October to +14.0% in March, although longer booking lead times may be overstating pacing beyond the next one to two months. Holiday pacing is mixed: Thanksgiving is tracking in line with its surrounding weeks (+15.2%), Christmas trails them (+7.7% vs. +12.3%), and New Year’s leads (+23.2%), helped by the holiday falling on a Friday. Recent performance supports the outlook: netting out the Labor Day calendar shift, U.S. demand grew 2.1% across August and September, while September ADR rose 7.2%.